Down payment , Insurance & other costs FHA vs. Conventional Loans: Key Differences Explained
In this article, we will explore the differences between FHA and conventional loans, focusing on down payment requirements, mortgage insurance, and monthly costs. Understanding these factors can help you make informed decisions about your home financing options.
When considering home financing options, the choice between an FHA loan and a conventional loan often arises. Each has its advantages and disadvantages. The Federal Housing Administration (FHA) backs FHA loans, which generally offer lower down payment options. Conventional loans, on the other hand, are not insured by any government agency and can have stricter qualification criteria. Understanding these differences is crucial for making the best decision for your situation.
The primary difference between FHA and conventional loans lies in their requirements and insurance costs. FHA loans allow for a lower credit score, which is beneficial for first-time buyers or those with limited credit history.
In contrast, conventional loans typically require higher credit scores but may provide more flexibility in terms of down payment amounts once you qualify. Let’s break down the specifics:
With FHA loans, mortgage insurance premiums (MIP) are mandatory regardless of your down payment amount. This can increase your monthly costs significantly over time.
Conventional loans may require PMI if your down payment is less than 20%. However, this insurance can be canceled once you reach a certain equity level in your home.
Due to higher insurance costs, monthly payments on FHA loans can be higher than those for conventional loans with similar loan amounts. It's essential to calculate these costs based on your financial situation.
Samantha was a first-time homebuyer with a credit score of 620. She found an FHA loan appealing because of the low down payment option. After her research, she realized her monthly payments would be manageable despite the MIP costs. However, she also understood that if she could improve her credit score slightly, a conventional loan might provide a better long-term financial outlook.
Want to explore what loan option suits you best? Reach out to me!
John and Maria owned their first home and wanted to upgrade. They had built up equity in their home but were hesitant to use it for a new purchase due to market fluctuations. They opted for a conventional loan with a larger down payment to avoid PMI altogether. Their decision paid off with lower monthly payments compared to FHA options they had initially considered.
Mark was an investor looking to purchase multiple rental properties. He discovered that while FHA loans were accessible for personal use, they were not ideal for investment properties due to stricter occupancy rules. Instead, he pursued conventional financing options that allowed him to leverage his existing assets while maintaining cash flow flexibility.
If you're uncertain about which path to take, I’m here to help you navigate your options!
The main benefit is the low down payment requirement and more lenient credit score standards, making it accessible for many buyers.
Yes, if your equity increases and your credit improves, refinancing into a conventional loan is possible and may reduce your monthly payments.
Yes, besides MIP, there may be upfront fees associated with closing that can add to initial expenses.
Your choice depends on your financial situation, credit score, and how long you plan to stay in the home. Consulting with a mortgage advisor can provide clarity.
Generally speaking, yes—FHA loans are designed for those with lower credit scores and can be more accommodating overall in terms of qualifications.
LUCIA LLERENA specializes in helping individuals understand their home financing options better. If you're contemplating whether an FHA or conventional loan suits your needs best or have any other mortgage-related questions, feel free to get in touch!
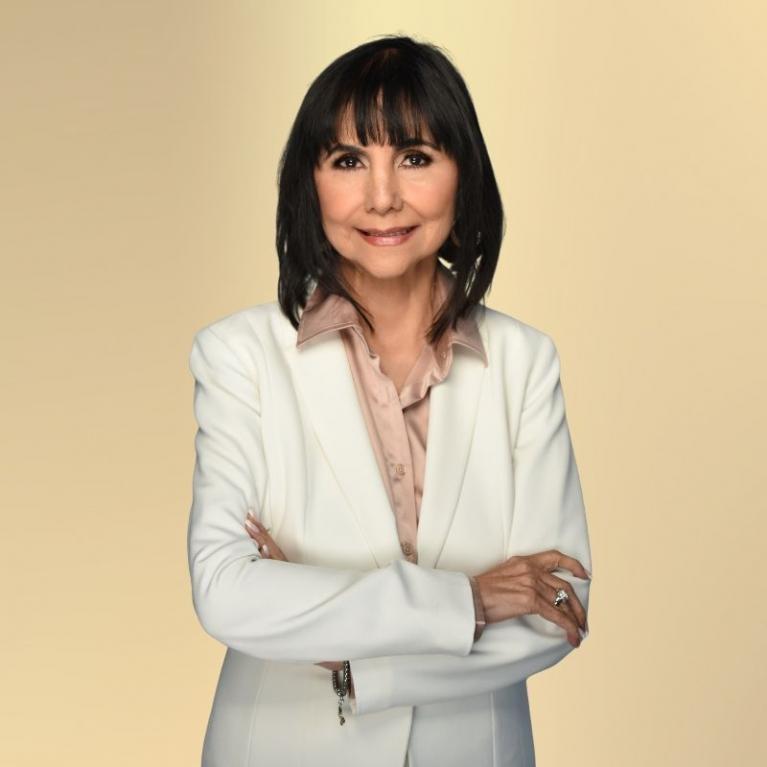
Originally from Peru, I bring an international background and over two decades of experience living in South Florida. My journey through Canada and Texas shaped my understanding of diverse markets and multicultural clients — perspective that today strengthens the way I represent buyers, sellers, and investors.
I believe real estate is more than a transaction. It’s about strategic decisions, long-term vision, and guiding each client with clarity, professionalism, and care.
Closing Times: Foreclosure vs. Traditional Sales
This article compares the time it takes to close properties in foreclosure versus traditional sales. It explores the processes, highlights key differences, and presents real-life case studies to illustrate various experiences. Practical insights help buyers make informed decisions.
Understanding Florida Property Taxes: A Practical Guide
This article explores local property taxes in Florida, focusing on how they are calculated based on assessed values and millage rates. It includes real-life case studies to illustrate the impact of exemptions and offers practical advice for homeowners and investors.
Navigating Property Taxes in Miami
Understanding property taxes in Miami involves grasping property value assessments, exemptions, and the millage rate. Homeowners can navigate potential costs by learning how these factors impact their tax bills, ensuring informed decisions in real estate.